BUYInitiation
Cenergy Holdings S.A.
Euronext Athens · CENER · Greece
Executive summary
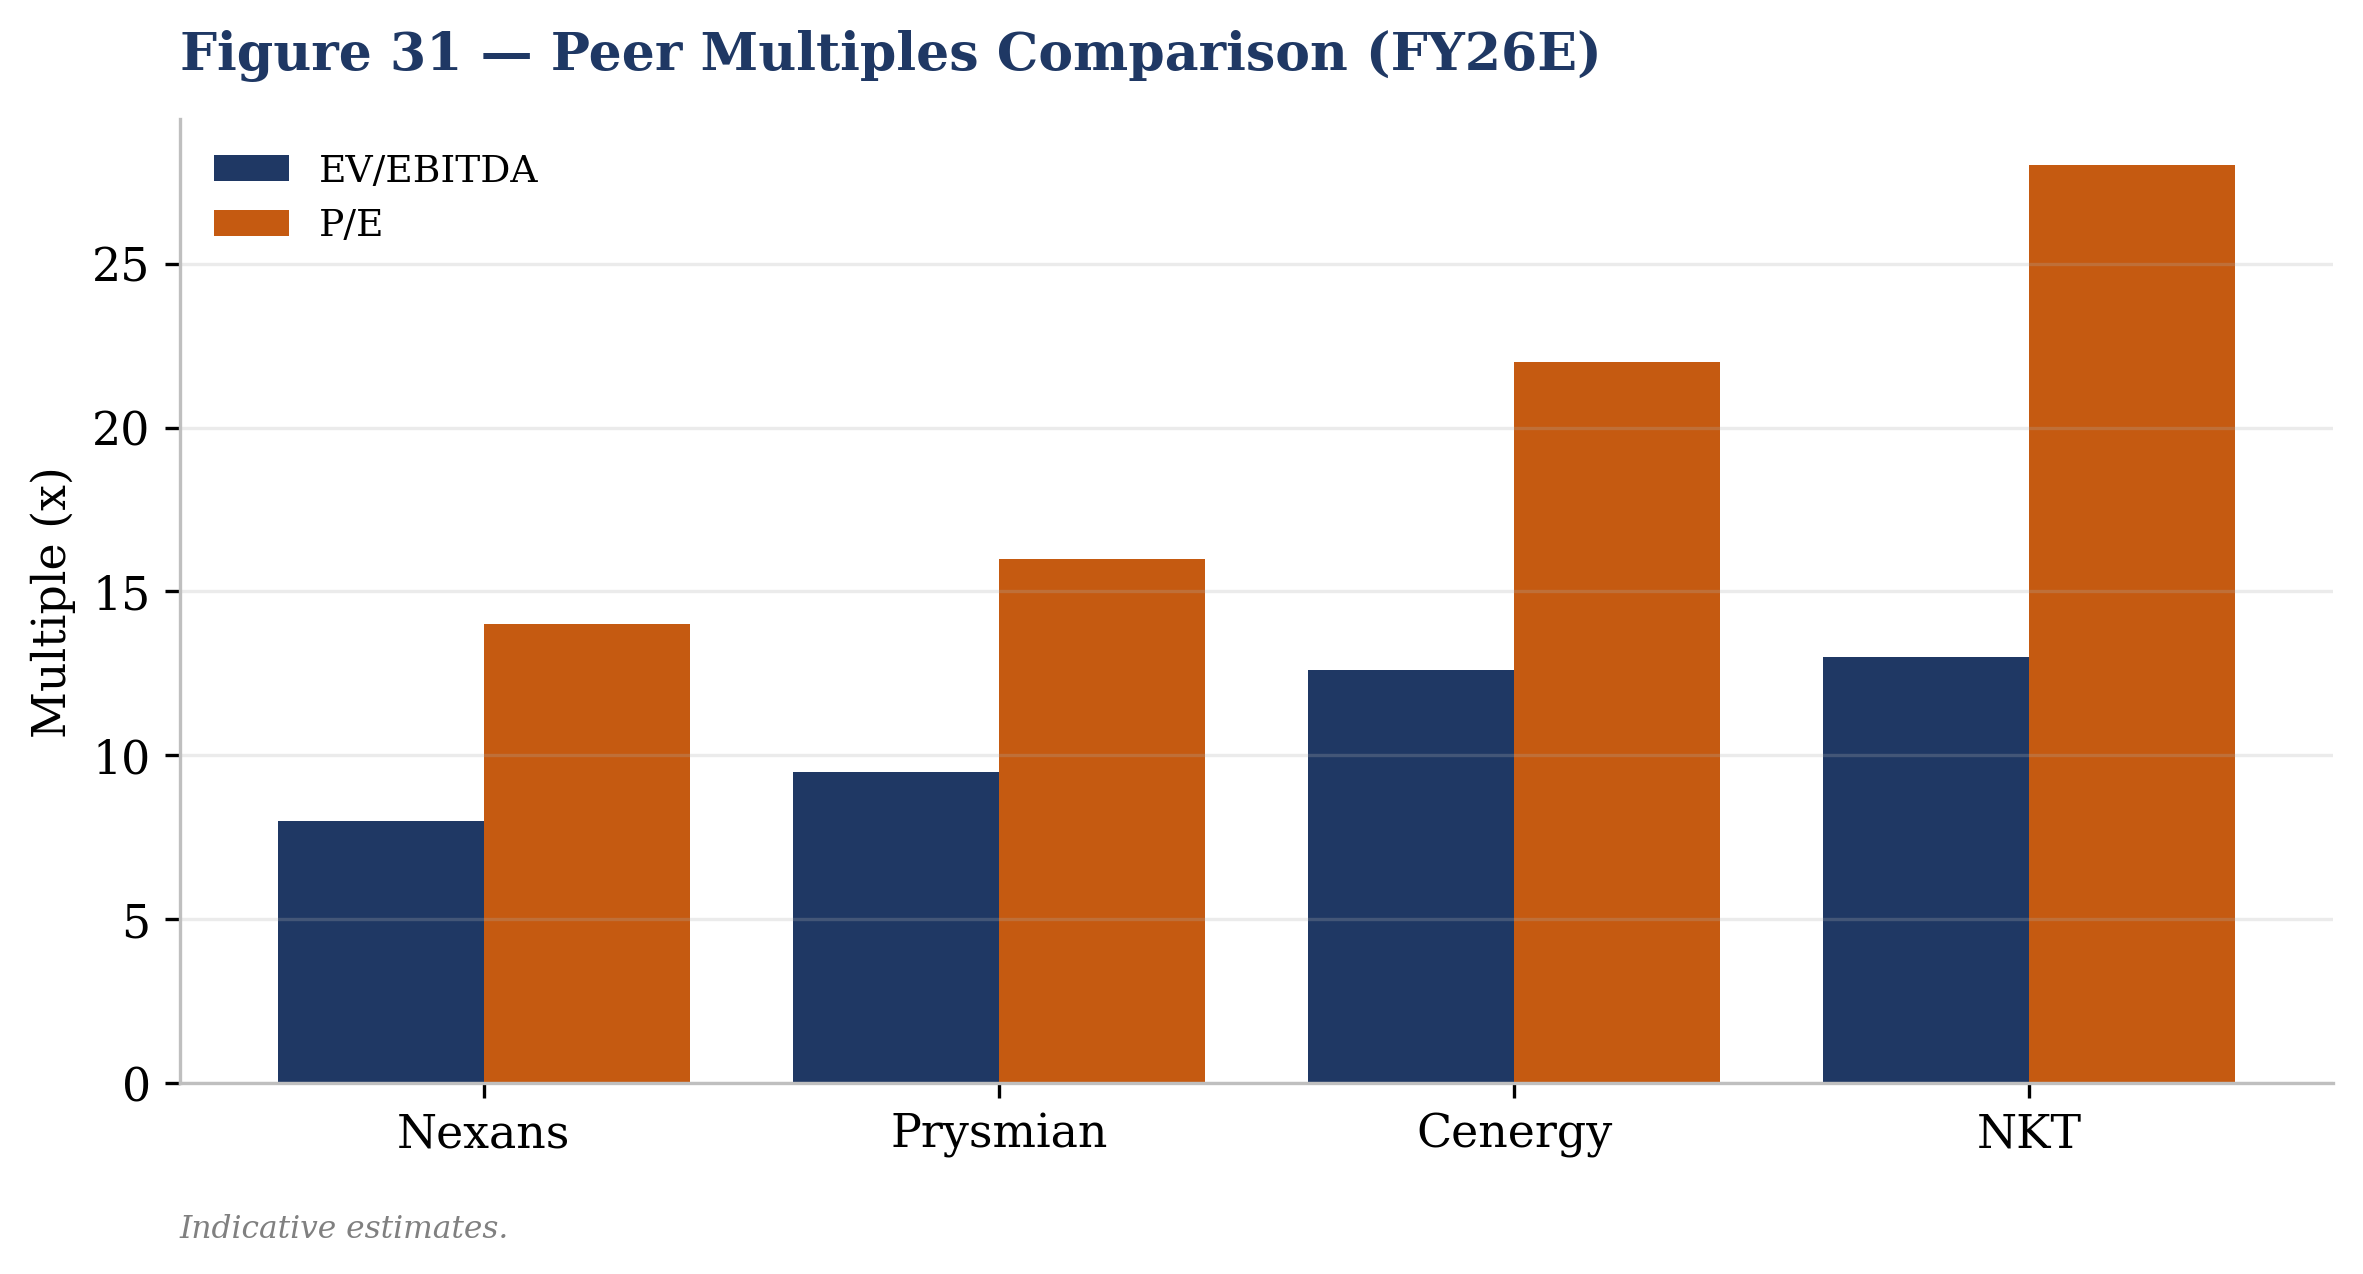
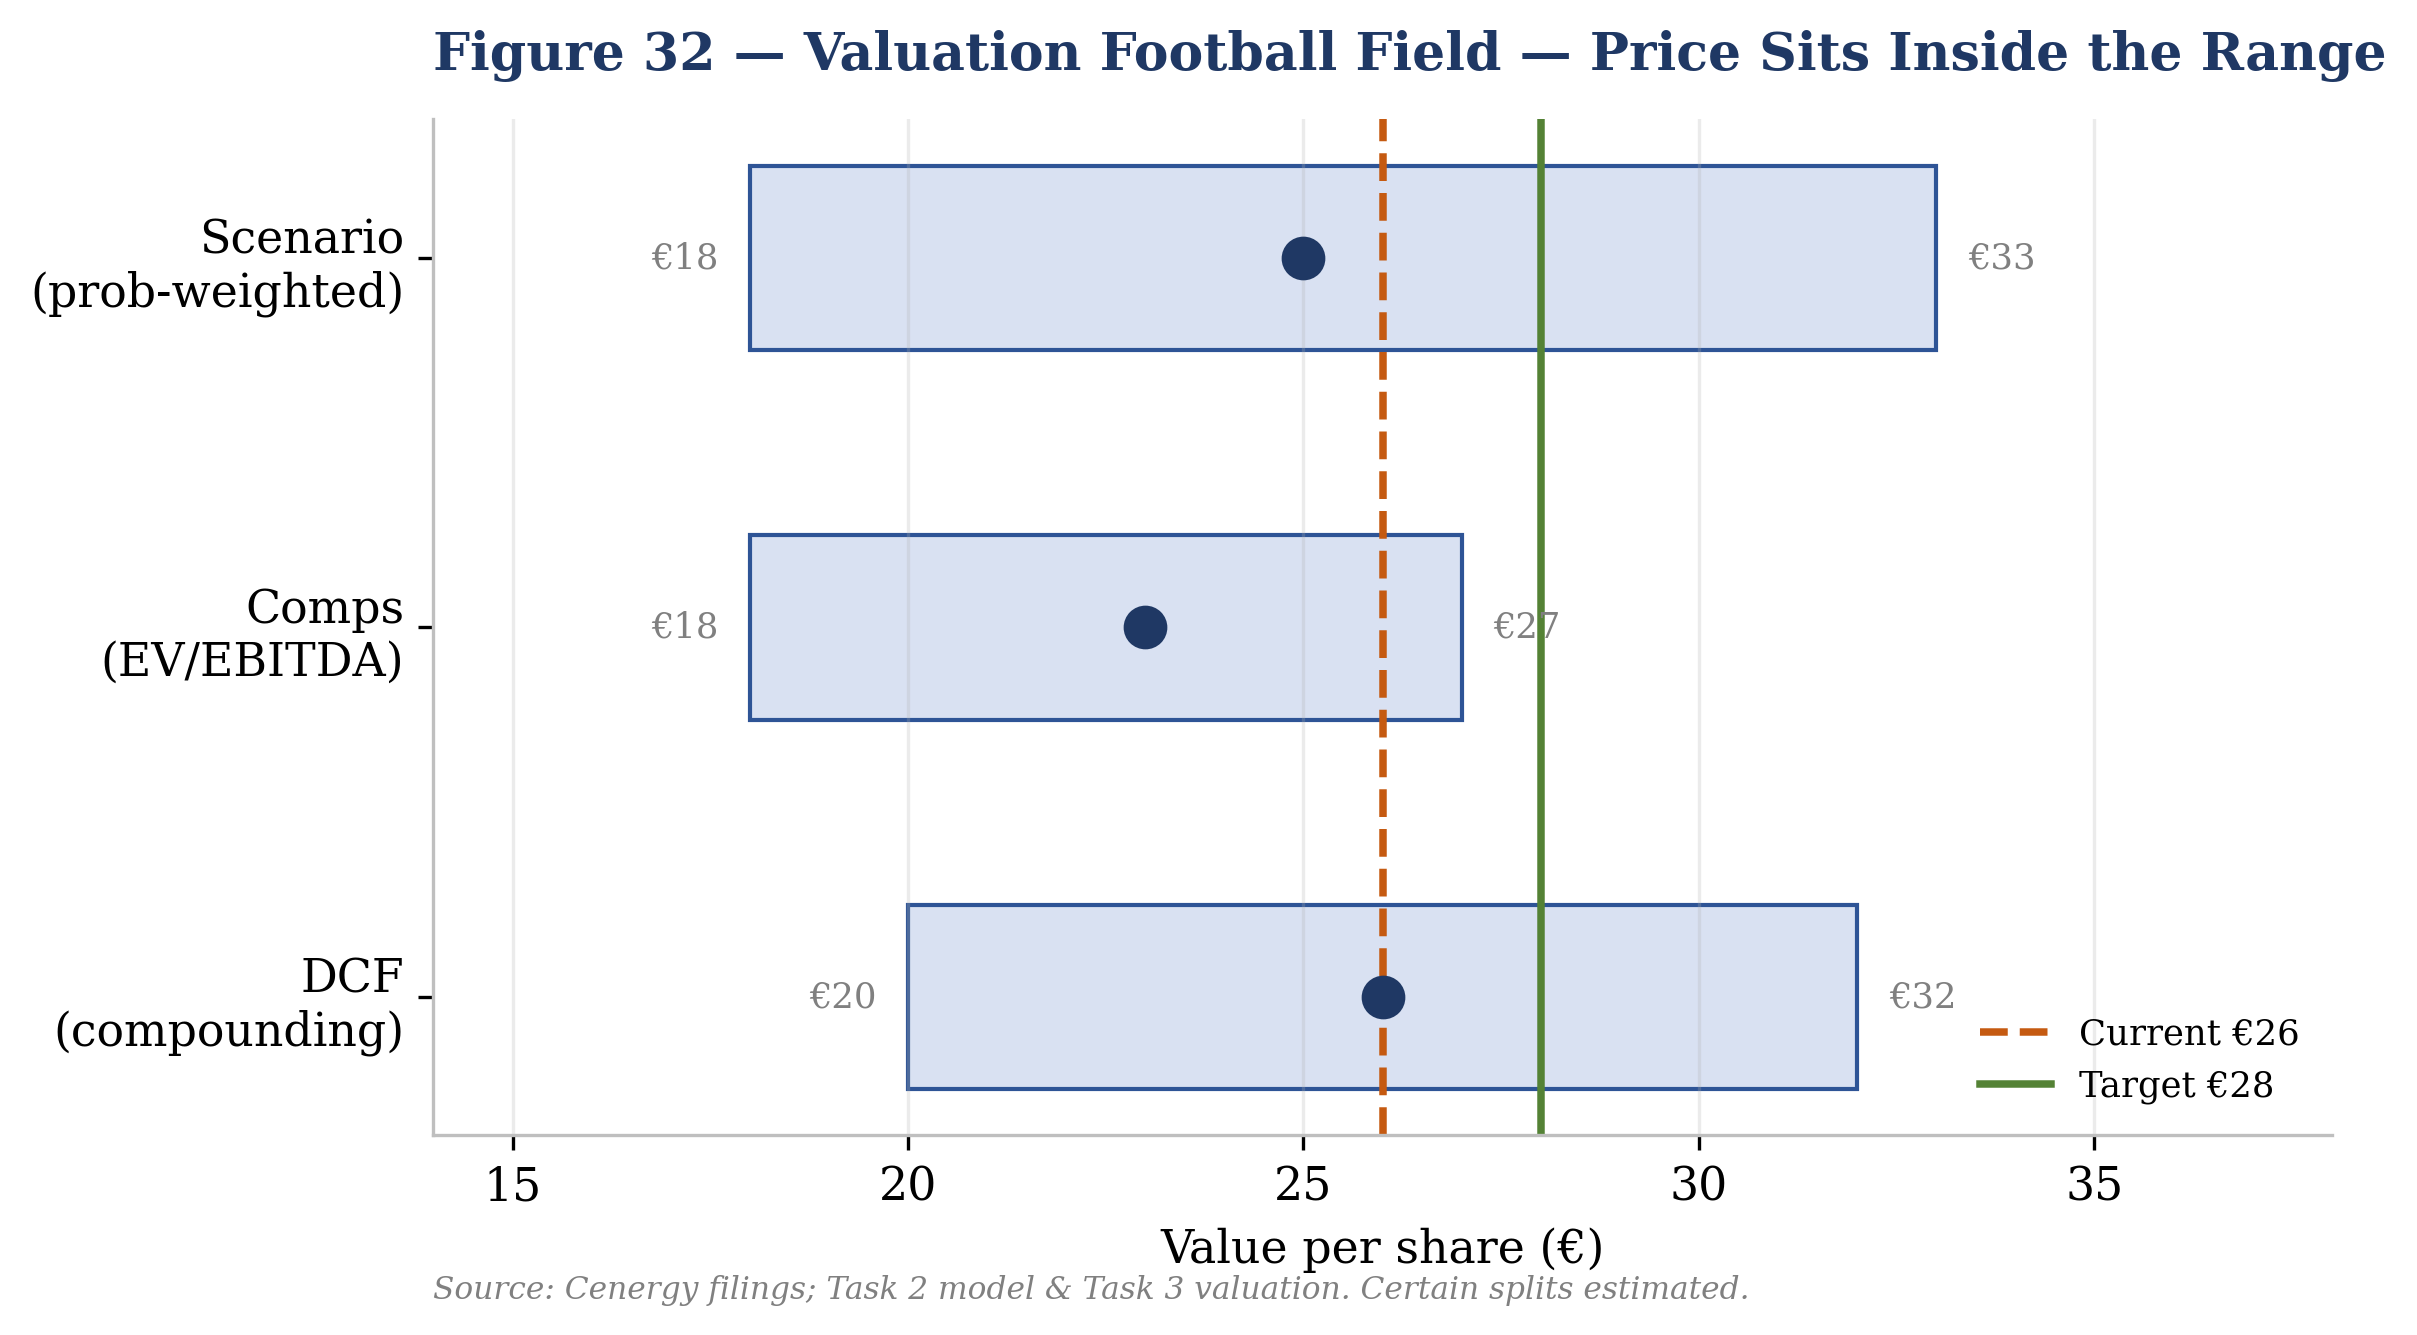
Highest-quality name in our coverage , a structurally-advantaged play on Europe's grid & offshore-wind build-out, with a fortress balance sheet that de-levers to net cash by FY2029 and ~13% EPS compounding. But quality is largely in the price at ~12.6x EV/EBITDA and ~22x earnings. Base-case DCF (~€26), scenario-weighted (~€25) and comps all bracket the current price. BUY, €28 target; accumulate on weakness toward €20–22.
- ▪Cables levered to Europe's multi-decade grid & offshore-wind supercycle (HVDC, subsea, interconnectors)
- ▪Scarcity economics in high-voltage/subsea protect margins; €3.38bn backlog (>1.5x revenue) gives visibility
- ▪Self-funding compounder: net debt €152m de-levers to net cash by FY2029; uFCF €96m→€329m
- ▪Cables margin expanding to ~18.8%; pipes modeled conservatively (FY25 "annus mirabilis" won't repeat)
- ▪Fairly valued: premium multiple already prices the good news, so Buy
Key exhibits
Source: Mētis Research.
Source: Mētis Research.
Risks
- ▪Offshore-wind project delays/cancellations (cost inflation, permitting, financing)
- ▪Steel-pipes cyclicality; FY25 ~€108m Corinth peak margin unlikely to repeat
- ▪Cable industry capacity additions erode current pricing tightness
- ▪Tier-two scale disadvantage vs Prysmian/Nexans/NKT
- ▪Premium multiple → de-rating risk; Viohalco majority control / small free float
Catalysts
- ▪New HVDC/subsea awards (following Corinth–Kos, East Anglia TWO, BC-Wind)
- ▪Margin accretion as subsea/HVDC mix scales
- ▪Hartlepool UK LSAW ramp; CCS/hydrogen pipe wins (HyNet, Porthos)
- ▪2026 EBITDA guidance upgrades (now €390–420m); FY26/H1 results
- ▪Move to net cash, rising dividend, potential buyback
Downloads
Full initiation report, the fully-linked Excel model, and the source repository.
Independent research for informational and educational purposes only; not investment advice or a solicitation. See the full disclaimer & methodology.
Implied return
+22.8%
Target vs. last price